Quick Answer: Yes, an SBA 7(a) loan may be used to finance a partial or complete change of business ownership, including transactions involving owner-occupied commercial real estate. Approval depends on the transaction structure, property ownership, business cash flow, valuation, borrower qualifications, and lender requirements.
Buying out a partner’s share of commercial property can protect your business location and give you greater control over the company’s future. However, SBA financing depends on more than the property’s value. The lender must review what is being purchased, how the business and real estate are owned, and whether the remaining owner can support the new debt.
This article explains how an SBA loan may be used for a commercial property partner buyout, which loan program generally fits, and what you should prepare before applying. For a broader overview of ownership-change financing, visit LoanBud’s guide to SBA partial buyout loans.
How Does a Commercial Property Partner Buyout Work?
A partner buyout occurs when one owner purchases some or all of another owner’s interest. When commercial property is involved, the transaction may include:
- The departing partner’s ownership interest in the operating business
- Their interest in the commercial property
- Equipment, inventory, goodwill, or other business assets
- Existing debt associated with the business or property
- A combination of business and real estate interests
The legal ownership structure matters. The operating business may own the building directly, or a separate limited liability company may own the property and lease it to the business.
A lender will need to understand both entities, the ownership percentages, existing debts, what is being transferred, and what the buyer will own after closing.
Which SBA Loan Program Is Typically Used?
SBA 7(a) Loans
The SBA 7(a) program is generally the most flexible option for a partner buyout. According to the U.S. Small Business Administration, 7(a) loan proceeds may be used for complete or partial changes of ownership, real estate, equipment, working capital, and multiple-purpose transactions.
An SBA 7(a) loan may be appropriate when the transaction includes:
- A partial or complete business ownership change
- Owner-occupied commercial real estate
- Equipment, inventory, or other business assets
- Eligible transaction and closing costs
- Multiple financing needs within one transaction
The maximum standard SBA 7(a) loan amount is generally $5 million. Total transaction financing may be higher when an SBA loan is combined with conventional financing or other approved funding sources.
Loans involving eligible real estate may receive repayment terms of up to 25 years, although the final term depends on how the proceeds are used and the lender’s underwriting.
SBA 504 Loans
SBA 504 loans primarily finance eligible fixed assets, such as owner-occupied commercial real estate and long-term equipment. They are not generally as flexible as 7(a) loans for purchasing a partner’s ownership interest, goodwill, inventory, or working capital.
A 504 loan could potentially be relevant when the transaction is structured as an eligible real estate acquisition. However, a Certified Development Company and participating lender must review the exact structure.
For most transactions combining a partner buyout with business assets or an ownership change, the SBA 7(a) program is usually the more practical starting point.
What Determines the Partner’s Buyout Price?
The buyout price should not be calculated by simply multiplying the partner’s ownership percentage by the property’s gross value.
The calculation may need to account for:
- The property’s independently appraised value
- Outstanding mortgage and lien balances
- Each partner’s ownership percentage
- Capital contributions made by each partner
- Business and property-related liabilities
- Any ownership discounts or adjustments
- The value of other business assets included in the sale
- Terms contained in the partnership or operating agreement
For example, if a property is worth $1.5 million but has an $800,000 mortgage, its gross equity would be approximately $700,000 before transaction costs or other adjustments. A partner’s percentage would normally be applied to the adjusted equity—not automatically to the property’s full $1.5 million value.
A qualified attorney, accountant, appraiser, and SBA lender should review the final valuation and deal structure.
What Requirements Must the Transaction Meet?
Although requirements vary by lender and transaction, applicants should generally expect the following.
Eligible Operating Business
The business typically must:
- Operate for profit in the United States
- Meet SBA size requirements
- Be an eligible type of business
- Demonstrate sufficient cash flow to repay the loan
- Be creditworthy under SBA and lender standards
Owner-Occupied Property
SBA financing is intended for property used by the operating business, not passive real estate investment.
For an existing building, the operating business generally must occupy at least 51% of the property. Additional rules may apply to new construction, multiple tenants, or properties owned by a separate entity.
Acceptable Ownership Structure
The lender must confirm:
- Who currently owns the business
- Who owns the commercial property
- Which ownership interests are being purchased
- Whether the seller will retain any ownership
- How ownership will look after closing
- Whether all required personal guarantees will be provided
Demonstrated Repayment Ability
The buyer and operating business must show that they can support the proposed loan after the departing partner exits.
Lenders may review:
- Business tax returns
- Profit-and-loss statements
- Balance sheets
- Business debt schedules
- Personal financial statements
- Personal and business credit histories
- Financial projections
- The departing partner’s role in generating revenue or managing operations
If the departing partner is important to the company’s operations, the lender may also request a transition or succession plan.
Documents You May Need
Preparing the following documents early can help prevent delays:
- Partnership, shareholder, or operating agreement
- Draft purchase or buyout agreement
- Current ownership records
- Business and property tax returns
- Year-to-date financial statements
- Business debt schedule
- Existing mortgage documents
- Commercial leases
- Property appraisal or preliminary valuation
- Environmental reports, when required
- Buyer’s personal financial statement
- Resumes for remaining owners and managers
- Transition or succession plan
- Entity formation and organizational documents
Your lender may require additional documentation based on the property, transaction size, industry, and ownership structure.
Steps to Finance the Buyout
1. Review the Existing Agreements
Start with the partnership, shareholder, operating, and real estate ownership agreements. These documents may establish valuation procedures, purchase rights, approval requirements, or restrictions on transferring ownership.
2. Identify What Is Being Purchased
Determine whether you are purchasing:
- An interest in the operating business
- A direct interest in the property
- An interest in a separate real estate entity
- A combination of business and property assets
This decision affects the valuation, tax treatment, loan structure, and closing documents.
3. Obtain Independent Valuations
Depending on the transaction, the lender may require a commercial property appraisal, business valuation, or both. Do not rely solely on an informal price negotiated between the partners.
4. Prepare a Written Buyout Agreement
The agreement should clearly identify:
- The buyer and seller
- The ownership interest or assets being transferred
- The purchase price
- Existing debt being assumed or refinanced
- Payment terms
- Conditions for closing
- The seller’s responsibilities after closing
Have a qualified attorney prepare or review the agreement.
5. Apply With an Experienced SBA Lender
Partner buyouts involving commercial real estate can be more complicated than ordinary property purchases. An experienced SBA lender can evaluate the ownership structure, identify eligible uses of proceeds, and determine whether the transaction fits the 7(a) program.
Common Issues That Can Delay Approval
A partner buyout may encounter problems when:
- The parties disagree about the property or business value
- The ownership records do not match the proposed transaction
- The property is primarily held for investment
- The business cannot support the new debt
- The departing partner performs essential duties without a replacement plan
- Existing liens or title problems have not been resolved
- The agreement does not clearly identify what is being sold
- The transaction combines eligible and ineligible uses of loan proceeds
Resolving these issues before underwriting can make the financing process more efficient.
Frequently Asked Questions
Can an SBA loan finance a partial partner buyout?
Yes. SBA 7(a) loans may finance eligible partial changes of ownership. The lender must review the post-closing ownership structure, business cash flow, guarantees, valuation, and other underwriting requirements.
Can I use an SBA loan if the property is owned by a separate LLC?
Possibly. SBA loans frequently involve an eligible passive company that owns property and leases it to an operating company. However, the ownership and lease structure must comply with SBA requirements.
Is a down payment required for an SBA partial buyout?
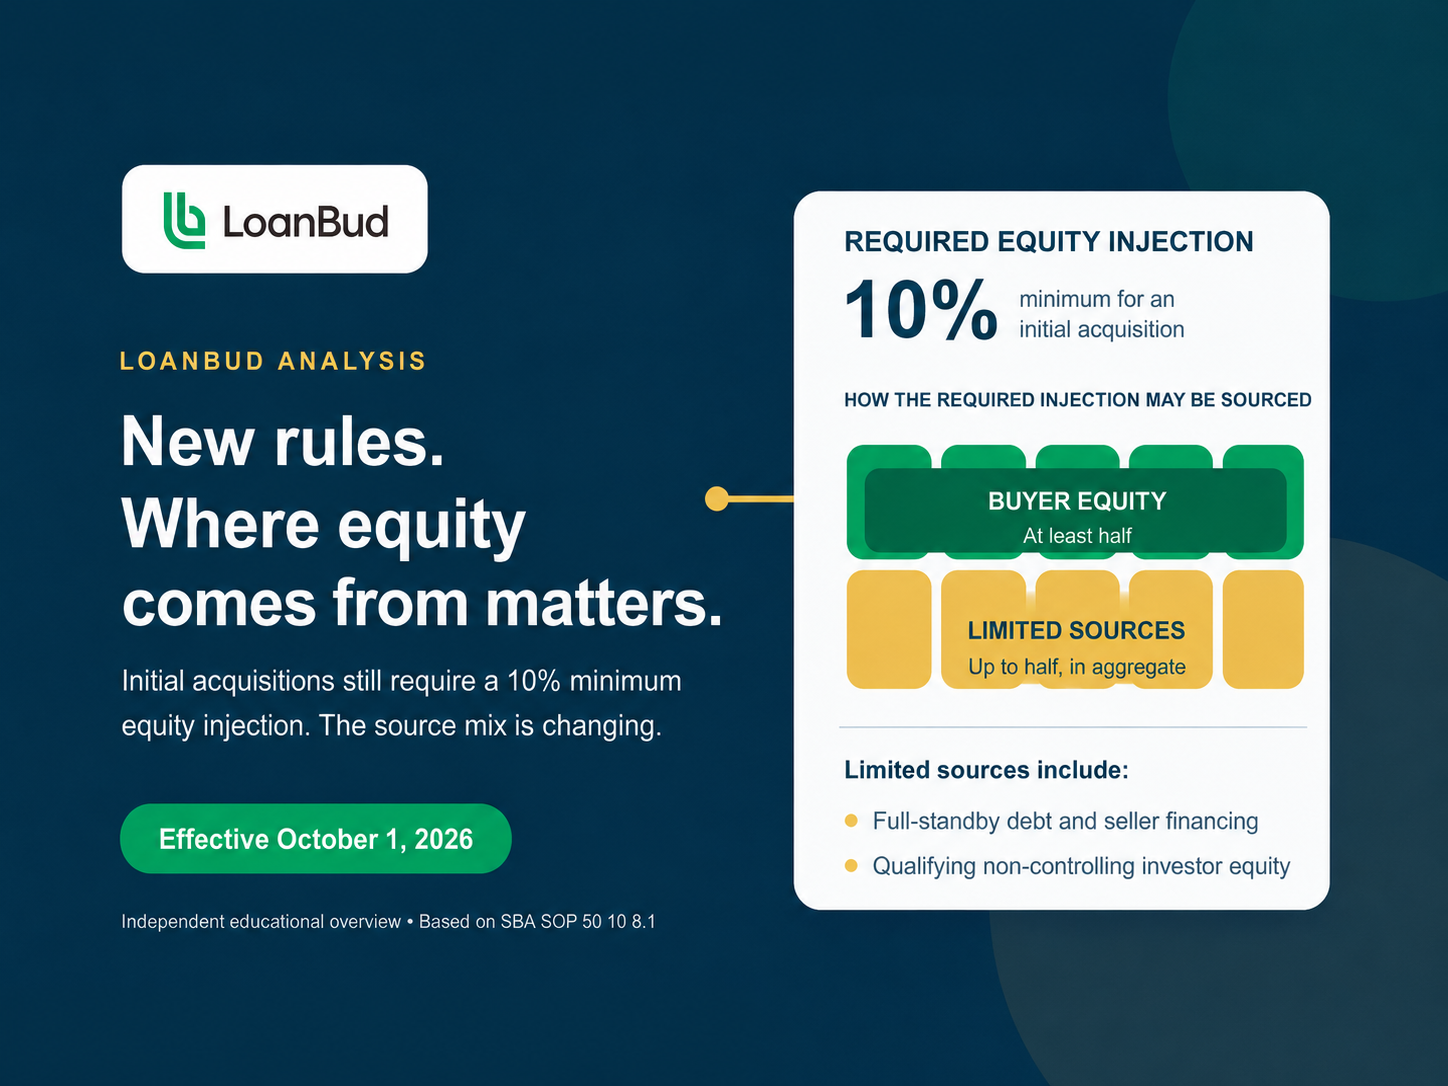
Some qualified partial buyouts may be structured with as little as $0 down. However, this is not automatic. Equity requirements depend on the transaction, loan size, business balance sheet, SBA rules in effect at the time, and the lender’s underwriting policies.
Do I need both a property appraisal and a business valuation?
You may. A property appraisal establishes the value of the real estate, while a business valuation evaluates the ownership interest and other business assets. The lender will determine which reports are required.
Can the departing partner remain involved?
Potentially, depending on the type of ownership change and the proposed post-closing structure. Any continuing ownership, employment, consulting, or management arrangement should be disclosed to the lender.
Explore Your SBA Partner Buyout Options
Buying out a partner’s share of commercial property can protect your location, simplify ownership, and give you greater control over the business. The key is structuring the transaction around the actual ownership interests, property equity, existing debt, and business cash flow.
LoanBud can help you explore SBA financing options for your proposed partner buyout.
Credit and collateral are subject to lender approval. Terms and conditions apply. This is not a commitment to lend. LoanBud is not affiliated with the SBA or any government agency. Programs, rates, terms, and conditions are subject to change without notice.