
Updated August 2026. The rules discussed below come from SBA SOP 50 10 8.1, which takes effect October 1, 2026. This article focuses primarily on initial business acquisitions. Other change-of-ownership structures may be treated differently.
The newest SBA loan rules include plenty of technical language. For buyers, sellers, business brokers, investors, and advisors, one change deserves immediate attention:
Buyers may need to bring more qualifying capital to an SBA-backed business acquisition.
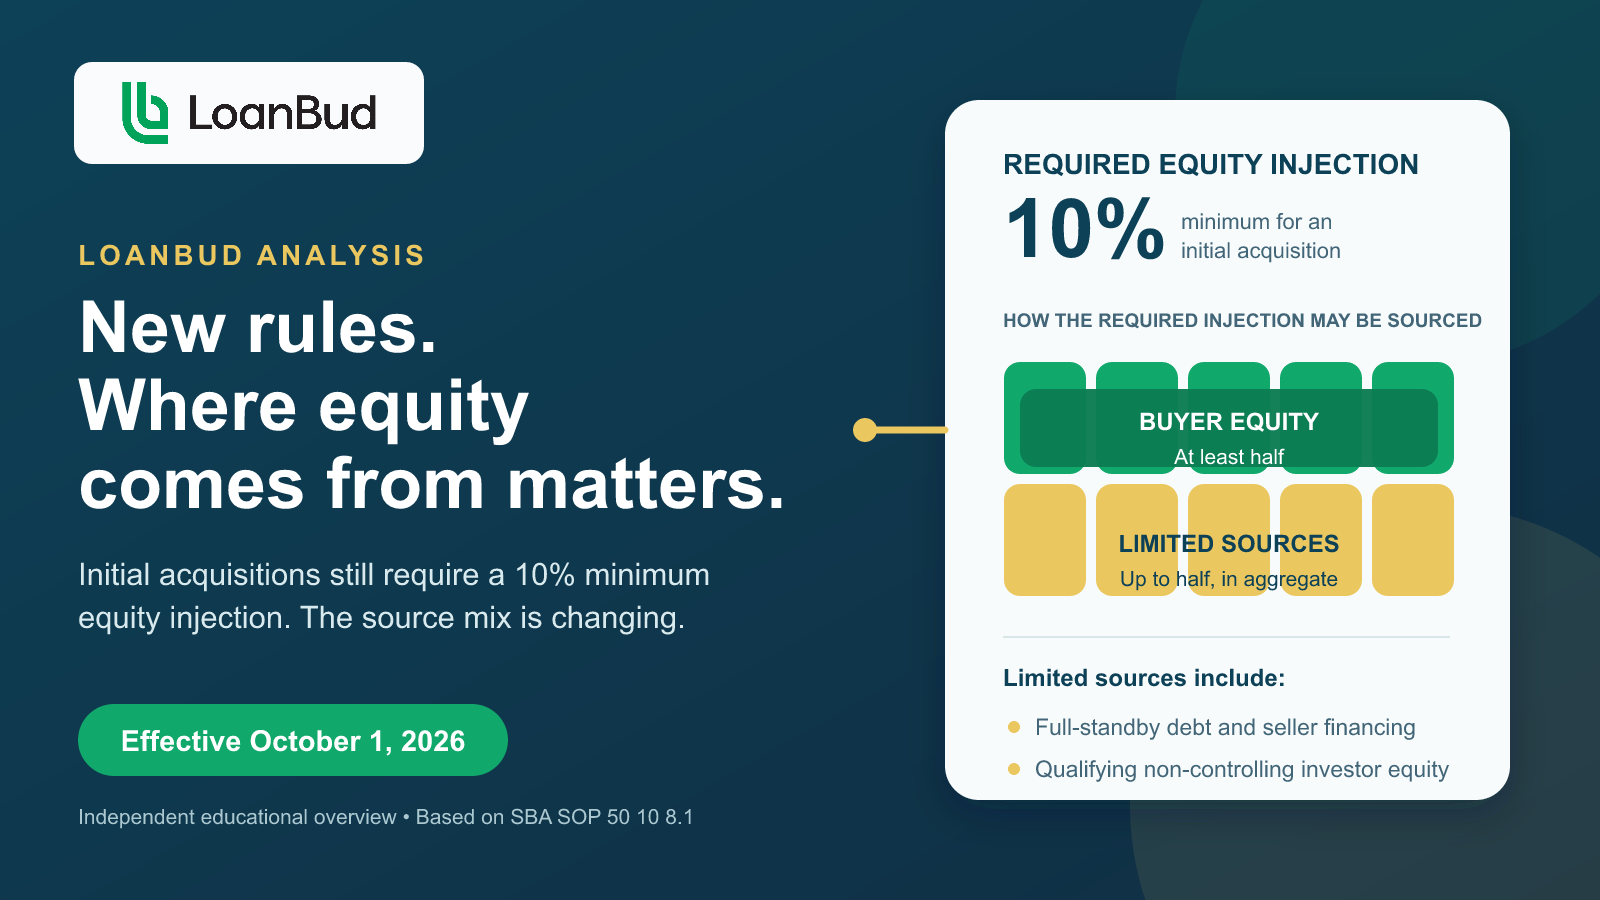
For an initial acquisition, the minimum equity injection remains 10% of the total project cost. The important change is how much of that injection can come from limited sources such as full-standby debt, full-standby seller financing, and qualifying non-controlling minority investor equity.
Under SBA SOP 50 10 8.1, those limited sources, individually or combined, generally may provide no more than half of the required equity injection. The rest must come from other eligible sources.
Put more simply: showing that you have 10% committed is no longer enough. You also need to show where every dollar of that 10% comes from.
What changes on October 1, 2026?
For an initial business acquisition financed with an SBA 7(a) loan, the minimum required equity injection is 10% of total project cost. The new SOP says that requirement cannot be reduced or eliminated for an initial acquisition.
The SOP separates equity sources into two groups.
Unlimited equity injection sources
The SOP lists the following as unlimited sources:
- Cash that is not borrowed, whether it is already on the business balance sheet or comes from another source
- Cash from a personal loan to a guarantor when repayment can be shown to come from a source other than the acquired business’s cash flow; salary paid by the business does not qualify as that outside repayment source
- Grants with no conditional repayment requirement, clawback, or other provision that could require repayment during the SBA loan term
Limited equity injection sources
The following sources may provide no more than half of the required equity injection, whether used alone or together:
- Debt on full standby, meaning no principal or interest payments during the term of the SBA 7(a) loan
- Seller debt that is subordinated to the lender and placed on full standby
- Qualifying non-controlling minority investor equity
That aggregate limit is the practical change buyers need to plan around. A seller note and passive investor capital may still be useful, but they cannot be used to replace the entire required injection.
A $2 million acquisition example
Assume an initial acquisition has a total project cost of $2 million.
- Total project cost: $2,000,000
- Required 10% equity injection: $200,000
- Maximum from limited sources in aggregate: $100,000
- Minimum that must come from other eligible sources: $100,000
For example, the buyer might use a full-standby seller note, qualifying minority investor equity, or another form of full-standby debt toward the injection. But all of those limited sources combined generally cannot exceed $100,000 in this example.
The remaining $100,000 must come from an eligible source outside that limited-source bucket.
This example is illustrative. The lender still needs to verify the project cost, the source and movement of funds, the terms of any debt or equity agreement, and the buyer’s post-closing financial position.
Why this matters for buyers
A buyer can have strong operating experience, find a healthy business, and line up investors who want to participate. The financing structure can still miss the mark if too much of the required injection comes from limited sources.
That changes the first financing question. Instead of asking only, “Do you have 10%?” buyers and their advisors should ask:
“Where is every dollar of the required equity coming from?”
The answer should be mapped before the buyer signs an LOI, not assembled after underwriting begins.
Buyers should be ready to document:
- How much unborrowed cash they can contribute
- Whether any personal loan will be repaid from a source outside the acquired business
- How much capital outside investors will contribute
- Whether those investors will own less than 20% and have no control over the operating business
- Whether seller financing or other debt will be on full standby
- How much liquidity will remain after closing
The last point matters. Using every available dollar for the injection may satisfy one requirement while creating a working-capital problem immediately after closing. A lender will still evaluate whether the business and buyer have enough liquidity to operate responsibly.
Could the new rule reduce the buyer pool?
It may, particularly for acquisitions that have historically depended on a large passive-investor contribution, a seller note, or both.
Some buyers can solve the gap by contributing more unborrowed cash or using another eligible unlimited source. Others may need to reconsider the purchase price, ownership structure, investor mix, or timing of the transaction.
The likely result is a sharper divide between an interested buyer and a financeable buyer.
A buyer may be willing to sign an LOI and may have people ready to invest. That does not automatically mean the proposed capital stack satisfies the SBA rules. Finding that out late can cost the buyer and seller weeks of work.
Buyer prequalification needs to go deeper
Headline liquidity is not enough. A useful prequalification process should test the proposed structure, not just the total amount committed.
Before a buyer pursues a business, the financing review should answer:
- What is the estimated total project cost?
- What equity injection is required for this specific type of change-of-ownership transaction?
- How much verified liquidity does the buyer control?
- What are the exact sources of the required injection?
- Are outside investors involved, and what ownership and control rights will they receive?
- Is seller financing part of the deal, and will it be on full standby?
- Do the limited sources stay within the aggregate 50% cap?
- How much liquidity will remain after the acquisition closes?
This is especially important before an LOI includes assumptions about financing, seller debt, or investor participation. A lender may require changes to documents that were already negotiated if the original structure does not comply.
What the rule means for business brokers
For business brokers, stronger buyer prequalification can protect the listing and the seller’s time.
A buyer who can produce proof of funds may still have an equity-source problem. Brokers do not need to underwrite an SBA loan, but they should know whether the buyer has spoken with an SBA financing specialist who understands the new rules.
Useful early questions include:
- Has the buyer’s liquidity been verified?
- How much of the injection comes directly from the buyer?
- Are passive investors or seller financing being counted toward the injection?
- Has a lender or financing specialist reviewed the proposed structure?
A deeper prequalification process can help brokers avoid spending months on a buyer whose capital structure was never workable.
What the rule means for sellers
The highest offer is not always the strongest offer if the buyer cannot support the required financing structure.
Sellers and their advisors may want more visibility into buyer prequalification before accepting an offer. That does not mean asking for every underwriting document. It means confirming that someone familiar with the new SOP has reviewed the buyer’s liquidity, investor participation, and proposed seller note.
Seller financing can still help. When properly subordinated and placed on full standby, seller debt may count toward part of the required injection. But it shares the aggregate 50% limit with other limited sources. It cannot simply replace all of the buyer’s required eligible capital.
What the rule means for passive investors
The new SOP also deserves close review from passive investors.
To qualify as a non-controlling minority equity investor under this provision, an investor must own less than 20% of the operating business and exert no control over it.
If the investment is used to satisfy the required equity injection, the investment cannot be subject to an agreement to repay the investor or make distributions that recover the investment before the SBA guaranty is released. The SOP also generally prohibits distributions to that investor until the SBA 7(a) loan has been paid off, except for distributions made solely to cover the investor’s tax obligations attributable to the business’s income.
Capital contributed beyond the required injection may be treated differently. The SOP says additional equity used for liquidity rather than the required injection may receive standard distributions, subject to lender agreements and any applicable financial covenants.
That distinction can materially affect an investor’s expected economics. Buyers should work through investor rights, distributions, control, and exit provisions before treating the investment as part of the required injection.
What buyers should do before signing an LOI
- Estimate the full project cost. Include the purchase price and every additional use of proceeds included in the loan request.
- Identify the transaction type. Initial acquisitions, business expansions, owner buyouts, ESOP transactions, and other structures do not all follow the same equity rules.
- Build a source-by-source equity schedule. Label each dollar as an unlimited or limited source.
- Review investor terms early. Ownership percentage, control rights, repayment provisions, and distribution rights can affect whether investor capital qualifies.
- Document seller debt correctly. A seller note counted toward the injection must meet the full-standby and subordination requirements.
- Protect post-closing liquidity. Do not build a structure that leaves the buyer without enough cash to operate the business.
- Have the structure reviewed before the LOI is final. Correcting the capital stack early is easier than renegotiating it during underwriting.
For related guidance, read Buying a Family Business With an SBA Loan: What to Know and SBA Partial Buyout Risks: Common Pitfalls and How to Avoid Them.
The bottom line
Beginning October 1, 2026, the source of a buyer’s equity will matter almost as much as the amount.
For an initial acquisition, buyers should still expect a 10% minimum injection. But limited sources such as full-standby debt, full-standby seller financing, and qualifying non-controlling minority investor equity generally cannot provide more than half of that requirement in aggregate.
That means some buyers will need more unborrowed cash or another eligible unlimited source. It also means brokers, sellers, and investors have more reason to test the capital structure before a transaction gains momentum.
LoanBud helps buyers and their advisors evaluate SBA financing structures early, while there is still time to solve a preventable capital problem. If you are planning an acquisition under the new rules, start with the sources of the equity, not just the headline percentage.
Source and compliance note: This article is based on SBA SOP 50 10 8.1, effective October 1, 2026, and was fact-checked in August 2026. It is general educational information, not legal, tax, accounting, or investment advice and not a commitment to lend. SBA requirements, lender standards, and transaction terms may change and are subject to lender review. LoanBud is an independent financial technology platform and is not affiliated with or endorsed by the U.S. Small Business Administration or any government agency.